 Individu
 Group

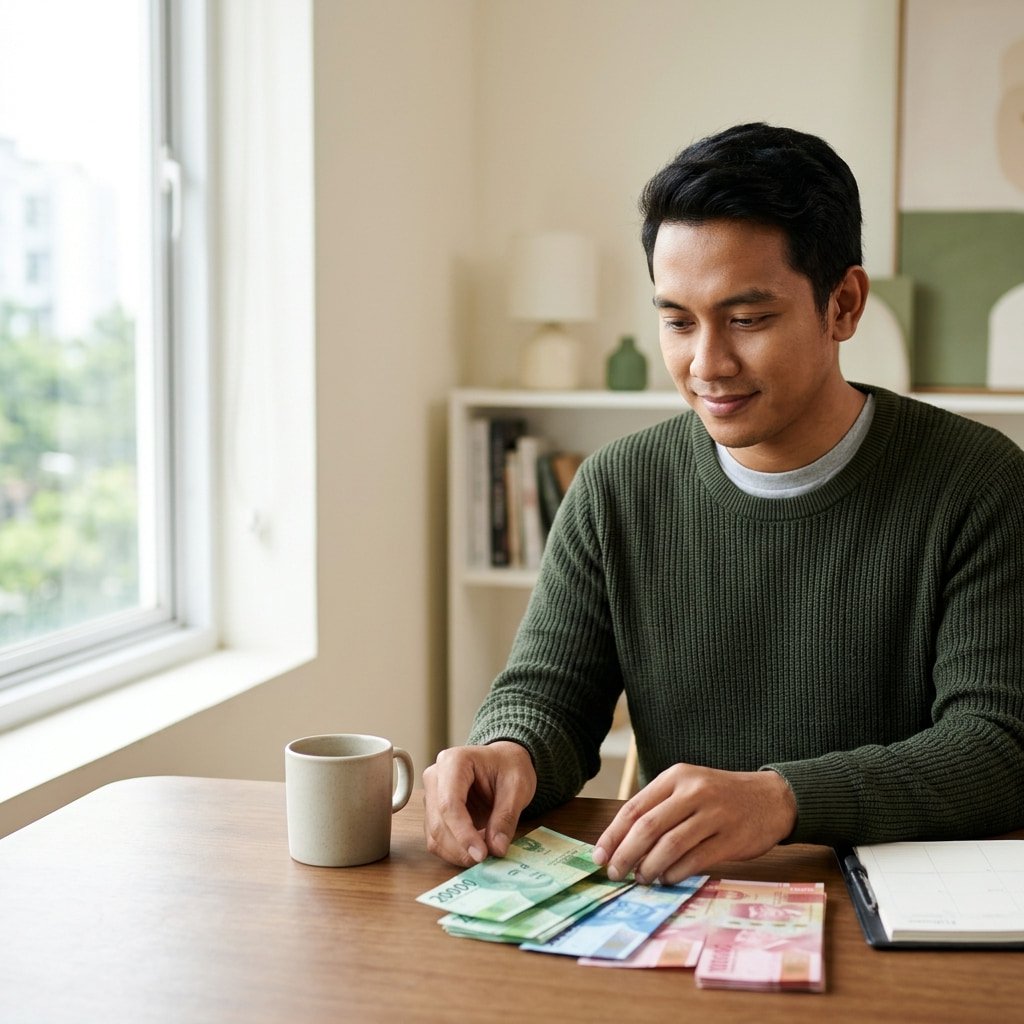
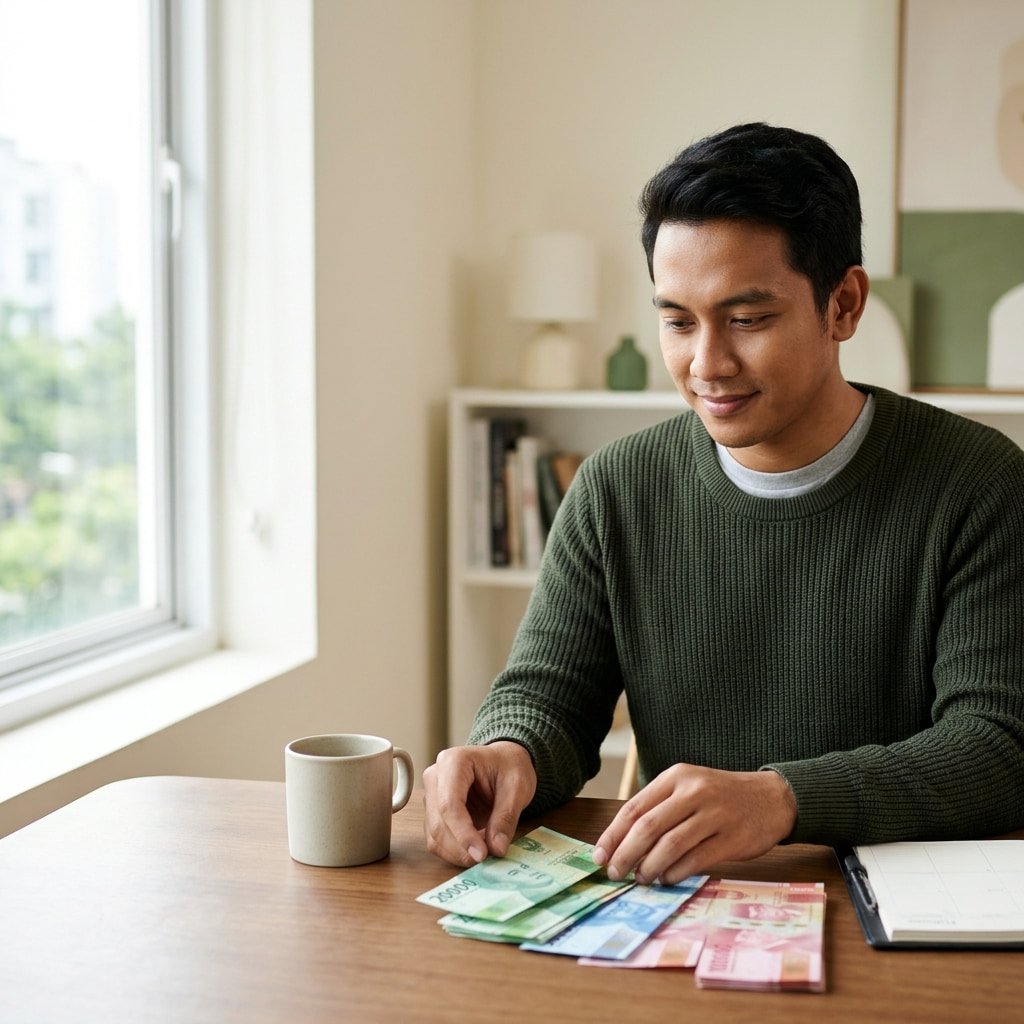
In daily life, financial stability often serves as the main foundation for peace of mind. Considering the continuously dynamic economic conditions—often reviewed in various reports, where economic growth is not always evenly distributed across all sectors—managing personal finances independently becomes a crucial precautionary step.Healthy finances do not mean you have to deprive yourself of all pleasures, but rather how you can wisely allocate your income for the present and the future.
Practical Tips for Managing Personal Finances:
Implement a Realistic Monthly Budget
Record All Your Regular Income and Expenses. A simple budget allocation like the 50/30/20 method (50% for basic needs, 30% for lifestyle, and 20% for savings/investments) can help keep cash flow balanced.
Prepare an Emergency Fund Early
An emergency fund is the main safety net when facing unexpected situations (such as health issues or sudden repairs). Try to set aside funds for at least 3 to 6 months of your monthly expenses.
Understand Financial Literacy and Protection
Besides investment, asset protection through the right financial products such as insurance or health protection is very important so that your finances do not suddenly falter when risks occur.
Avoid Consumer Debt
Use credit or financing facilities only for productive purposes (such as business capital or long-term valuable assets). Avoid debt for a consumptive lifestyle that can burden your monthly cash flow.
Others Articles